You've been saving for decades, and at some point the question changes from "how much can I put away" to "will this actually last." That's a much scarier question, because you don't get a do-over. If the plan is wrong, you find out when it's too late to fix it.
And retirement isn't one decision — it's dozens, all tangled together. When do you claim Social Security, and how much does that choice cost you if you get it wrong? Which accounts do you draw from first, and in what order, to avoid a tax bill that eats your withdrawals? What happens to your plan if the market drops significantly in your first few years of retirement — the exact window where a downturn does the most damage? Most people are left guessing at all of this alone, using a generic rule of thumb instead of a plan built for their actual numbers.
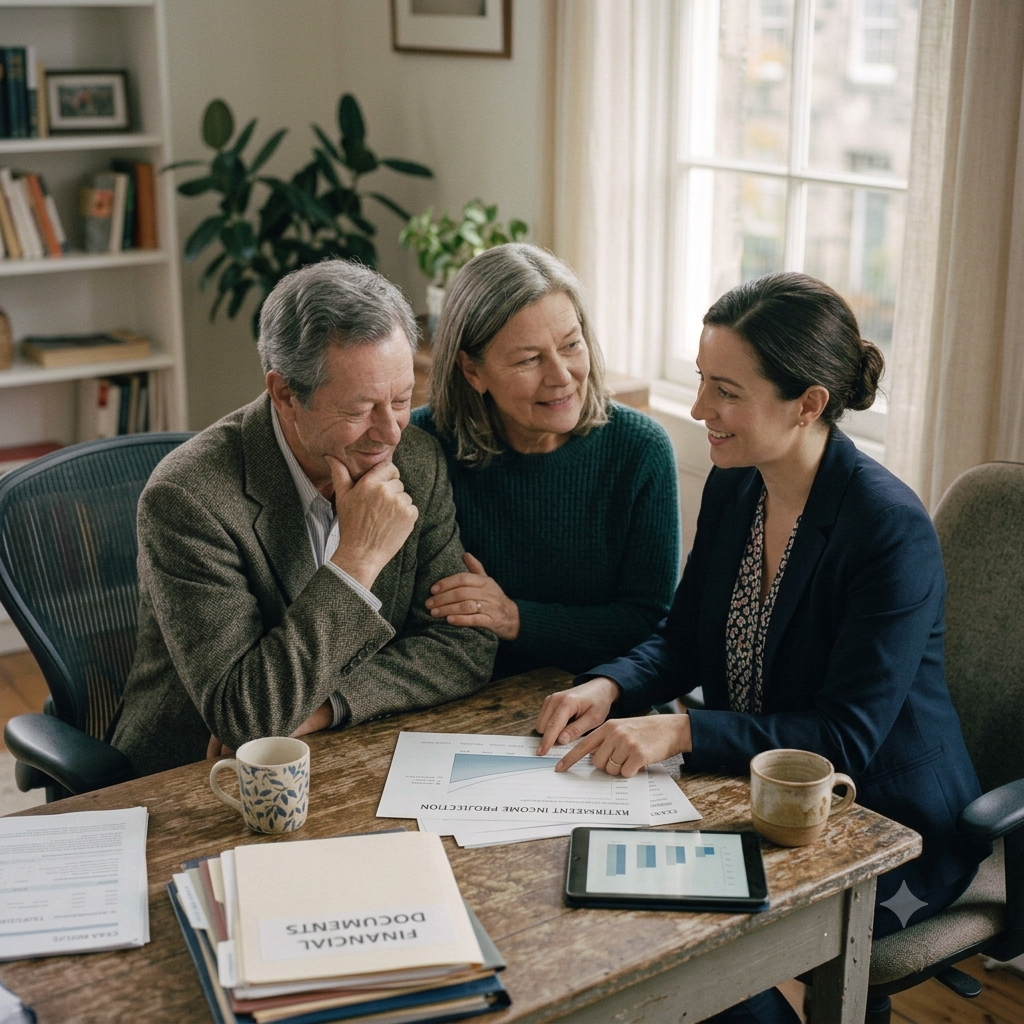
We build a retirement income plan specific to you — one that accounts for your actual expenses, your Social Security timing, your tax situation, and your risk tolerance, not a one-size-fits-all withdrawal rate.
You'll know exactly where your income is coming from, year by year, and why.We also plan explicitly for the risk that matters most in retirement: a bad market in the wrong years. That means structuring your withdrawals and your portfolio so a downturn doesn't force you to sell at the worst possible time. And because this plan connects directly to your tax and estate strategy, your retirement income is designed to work with the rest of your plan — not around it.
a satisfied client
Free consultation
30 Minutes, no obligation